| Updated:
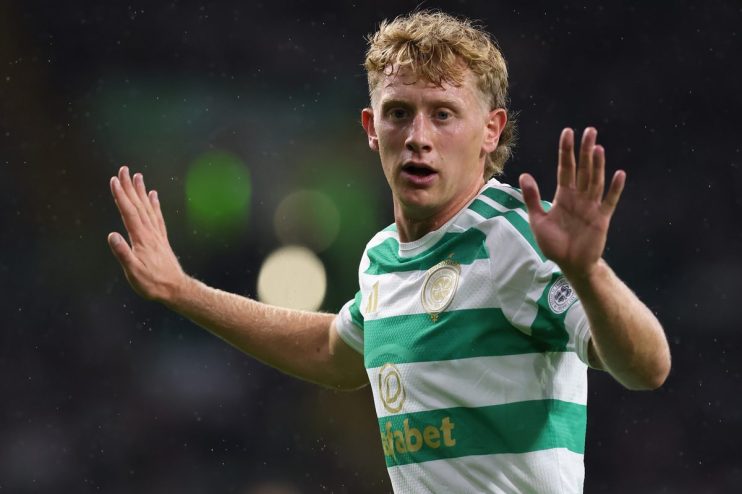
By most conventional measures, Celtic should be a model of how to run a football club. According to the club’s latest accounts, Celtic generated £143.6m of revenue and £33.9m of profit after tax, while finishing the year with £77.3m in cash.
Shareholders have benefited too. According to FactSet, Celtic shares have appreciated approximately 153 per cent since 2017, compared with around 56 per cent for the FTSE All-Share over the same period. With this financial discipline, Celtic have won 14 of the last 15 Scottish league titles, alongside eight of the last 15 Scottish Cups and eight of the last 15 League Cups.
Celtic appear to have achieved something football routinely says cannot be done: sustained sporting success alongside financial discipline. Yet many Celtic supporters are deeply unhappy.
The board itself acknowledged in its February interim report that, regardless of their domestic success, “mistakes have been made” with supporter groups demanding changes in governance, recruitment and the deployment of the club’s resources. Those tensions will possibly rise after another failure to reach the Champions League proper this season.
This creates an unusual conflict of objectives between shareholders and supporters. For shareholders, financial resilience and capital appreciation are legitimate measures of success. For supporters, trophies, European progress and maximising sporting ambition are measures of success.
Neither perspective is inherently irrational. The problem is that they do not point towards the same capital-allocation decisions.
Potential contradiction in regulation
Celtic sits outside the jurisdiction of England’s new Independent Football Regulator (IFR), making it an interesting test case. The IFR was created to protect clubs from financial distress, requiring them to demonstrate financial soundness, plan for shocks, and make sensible long-term financial decisions.
At the same time, clubs must consult supporters on matters including their strategic direction and business priorities, and take those views into account when making decisions. The Government has gone further, declaring that “football belongs to its fans”.
Celtic exposes a potential contradiction. What happens when supporters are consulted, and their preference is for greater sporting investment, while the financially prudent decision is to retain capital?
The regulator is designed largely around the historic problem of clubs taking too much financial risk in pursuit of success. Celtic presents the inverse problem: a club can arguably take too little sporting risk to satisfy its supporters while remaining a model of the financial behaviour regulation is intended to encourage.
This is where the regulatory problem becomes harder. If supporters demand greater investment in sporting performance while shareholders favour financial discipline, whose interests should prevail? The IFR mandates consultation; it does not specify how much influence those views should have over capital allocation.
Celtic is an unusual case – for now
This tension is not entirely new. Under Mike Ashley’s ownership, Newcastle United reported record profits and accumulated substantial cash reserves, while supporters protested that the club was investing too little in the team.
The irony is that Newcastle subsequently spent heavily, with almost £80m of net player expenditure across the next two transfer windows, and were relegated anyway. Ashley’s ownership was controversial, but the episode illustrates why the appropriate level of sporting risk is considerably easier to demand than to determine.
For now, Celtic remains an unusual case. Publicly traded football clubs are rare in Britain, but the ownership landscape is changing.
Private capital has become increasingly prominent in sport, while recent reforms have sought to make UK public markets more attractive for companies raising capital and for retail investors. The Government is simultaneously trying to channel more domestic savings towards productive investment and UK growth companies.
Against this backdrop, future public listings of football clubs may become more likely. If more clubs eventually combine institutional shareholders, supporter expectations and regulatory requirements for financial sustainability, Celtic’s current tensions may become considerably less unusual.
What happens when a club remains financially disciplined, shareholders prosper, and trophies continue to arrive, but supporters still believe it is not ambitious enough? Financial sustainability may be relatively easy to define. How much sporting risk a club should take, and who should decide, is considerably harder.
Danny F Hill is Assistant Professor of Finance at Providence College and founder of sports valuation consultancy Virsolus.
+ There are no comments
Add yours