| Updated:
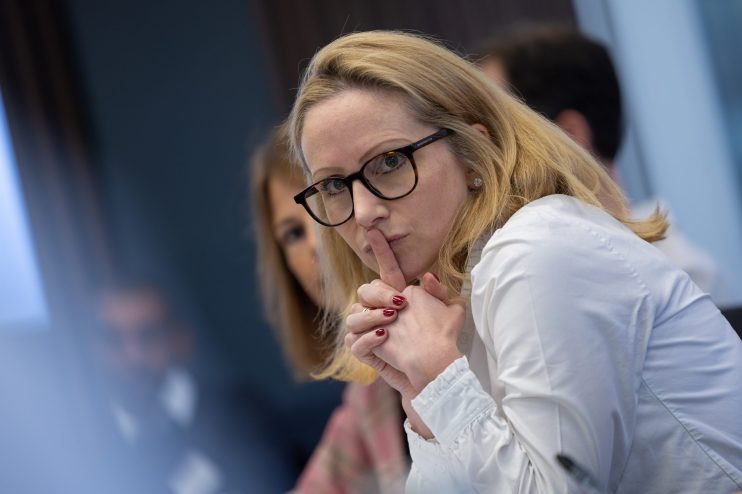
A top Treasury minister has opened the door to further capital markets reforms after saying the government’s job was not done in improving listing incentives.
Lucy Rigby, who serves as the economic secretary to the Treasury, otherwise known as City minister, told City AM the government was “continually looking for ways that we can ensure we’re being as competitive as possible”.
“We need to be cognisant of global competition and vigilant,” she said, adding “this isn’t just about our capital markets, but a much broader question for our financial services sector”.
In the 2025 Budget, then-Chancellor Rachel Reeves launched a stamp duty holiday, removing the 0.5 per cent levy on UK stocks for newly-listed companies in their first three years of trading.
“The reforms we’ve made to our capital markets are starting to bear some fruit… it’s definitely not a job done. I think it’s going to require a concerted and continued effort,” Rigby said.
She pointed to the £5.3bn IPO of Airtel Money – the City’s biggest listing in five years – as a sign of “renewed momentum”.
But the year has remained subdued for major IPOs with top names rumoured to be mulling a float either delaying or scrapping plans. Top bosses have continued to call for bigger swings to unlock an influx of new listings.
Rigby getting ‘many calls’ to do something about stamp duty
Fintech industry body Innovate Finance – which counts Revolut, Monzo and Zilch among its members – has called for stamp duty to be abolished entirely to “help reverse the decline in British ownership of UK companies”.
Rigby told City AM: “I wouldn’t be doing my job properly if I hadn’t heard many calls to do something about stamp.”
UK fintech investment hit a decade low in the first-half of the year at £1.8bn, down roughly two-thirds from the £5bn the year prior. Rigby said the figure was “not an amount of money to be sniffed at” but added the Treasury was making a “very considerable effort” to improve access to capital.
The minister met with top fintech unicorn chiefs last week, including the bosses of iwoca, Clearbank and Modulur.
A number of the industry’s top firms have ramped up lobbying efforts ahead of the Budget, with a key demand for the government to increase the threshold at which banks are hit with a sector specific tax.
Revolut and Monzo teamed up with Shawbrook, Aldemore and other challenger banks to lobby for the surcharge threshold to £500m, from £100m.
Rigby said: “Decisions on all forms of tax are for the Chancellor and he’ll make them in the context of the Budget”
She added: “There is no route to good growth in every postcode that doesn’t involve our world-leading financial services sector supporting the ambitions of the whole country.
+ There are no comments
Add yours